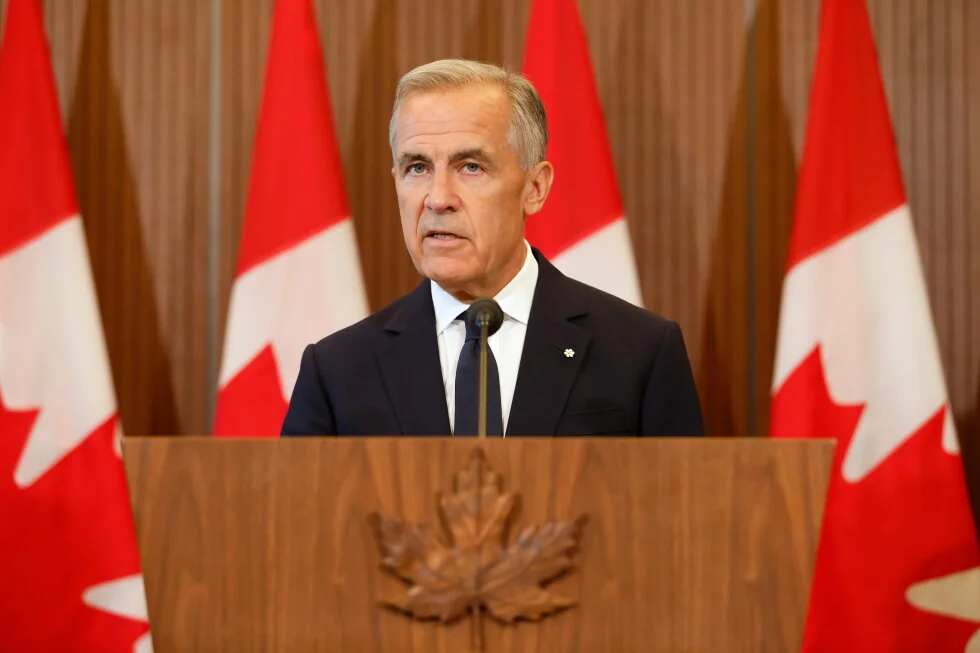
Fact Check: Trump Claims U.S. Banks Cannot Operate in Canada—That Is False
September 8th, 2026
Fact Check: Trump Claims U.S. Banks Cannot Operate in Canada—That Is False
🇺🇸 English
Upon being queried on Wednesday regarding the trade war with Canada, President Donald Trump erroneously contended that American banking institutions are precluded from conducting transactions with the nation to the north.
この発言は、トランプ氏が両国間における通商交渉再開の可能性について記者から問われた後、オーバルオフィスで開催された米国旅行業界の幹部らとの会合の席上で為されたものである。
専門家の分析によれば、米国の銀行は特定の規制上の制約に直面する可能性はあるものの、カナダ国内での事業活動そのものが法的に禁止されているというわけではない。
以下において、事実の全容を微細にわたり徹底的に検証し、その本質を明らかにする所存である。
トランプ氏はこう述べた。「彼らはここに銀行を有している。
カナダ銀行をはじめとする大手銀行すべて—実に壮大かつ優美な銀行群だ。
当地には主要銀行が六、七行存在すると見受けられる。
一方、我々は彼らの領土内に銀行を一切保有していない。
その理由を御存じか?
彼らがそれを許容していないからだ。」
事実として、カナダ銀行協会の広報担当者の見解によれば、現在、米国に本拠を置く15の銀行が、支店または子会社という形態でカナダ国内において営業活動を展開している。
専門家の分析では、特定の規制枠組みが米国の銀行にとって国境以北での競争を困難ならしめる可能性はあるものの、市場への参入そのものは自由であるとされる。
連邦準備制度が公表した最新の統計データに基づけば、米国内で事業を営むカナダ系銀行は8行存在する。
なお、カナダ銀行はこの範疇には含まれない—それは米国の連邦準備制度に相当するカナダの中央銀行であり、商業企業としての性格を有するものではないからである。
「米国とカナダの規制枠組みの相違に起因する複雑な相互作用から、不可避的に混乱が生起するものと見込まれる」と、カナダ・オンタリオ州ウォータールー大学の金融学教授ジェームズ・トンプソン氏は所見を述べた。
「米国の銀行機関がカナダ国内での営業許可を確かに取得しているのは事実であるが、その市場参入の様式如何によって、彼らの遂行可能な業務範囲は根本的に変容を余儀なくされるのである。」
In Canada, the banking sector is stratified into three distinct categories—Schedule I, Schedule II, and Schedule III—each delineated by ownership structure and regulatory scope.
Domestically owned financial institutions fall under the purview of Schedule I, a classification that encompasses six preeminent banks whose aggregate assets eclipse the combined holdings of the nation's twenty-eight smaller banking entities.
外国企業は、スケジュールIIまたはスケジュールIIIの銀行として営業する選択権を有する。
スケジュールII銀行は、カナダ国内に法人化された外国資本の子会社であり、国内資本の銀行と本質的に同等の銀行規制枠組みに該当する。
一方、スケジュールIII銀行は、カナダ国内に法人化されていない外国銀行の支店であり、より高い最低預金額要件などの規制上の制約に直面する。
米国資本の銀行の大多数は、スケジュールIIIの機関としてカナダで事業を展開している。
ナタリー・バージェロン氏、カナダ銀行協会の広報担当者は、カナダ国内で事業を展開する米国系銀行の支店および子会社が保有する総資産が約1,240億カナダドル(901億米ドル)に達し、これは外国銀行の子会社および支店が保有する全資産の過半数を優に超える割合を占めていると述べた。
「これらの金融機関は、法人融資および商業融資、財務アドバイザリー、クレジットカード商品、投資銀行業務、住宅ローン組成など、多岐にわたる金融サービスに特化しております」と彼女は言明した。
「彼らは、国境を越えた事業活動に従事する顧客層のみならず、カナダ国内の小売市場セグメントにも同様にサービスを提供しているのです。」
カナダ国内における事業展開を図る米国系銀行の範疇には、JPモルガン・チェース銀行、シティバンク、バンク・オブ・アメリカ、キャピタル・ワン、ウェルズ・ファーゴが包含される。
スケジュールIIおよびスケジュールIIIに分類される銀行は、いずれもカナダの銀行規制に起因する制約に直面している。
金融政策および金融システムの専門家であり、カナダのシンクタンクであるCDハウ研究所の社長兼最高経営責任者を務めるジェレミー・クロニック氏は、スケジュールIII銀行は15万カナダドル(7万2,529米ドル)未満の預金を受け入れることが法的に禁じられていると指摘した。
このことは、大多数の個人にとって、これらの銀行を小売銀行として利用することは事実上不可能であることを意味する。
さらに同氏は、スケジュールII銀行は外国の親会社から法的に独立した別個の実体であるため、独自の現地資本基盤および流動性構造を構築する必要があり、銀行経営の観点からすれば非効率的な選択肢であると補足した。
このような規制上の制約が、米国資本の銀行の圧倒的多数が国境を越えた事業展開を躊躇する根拠となっている可能性がある。
連邦準備制度理事会の統計によれば、米国内には3,700を超える国内資本の商業銀行が存在する一方で、カナダに拠点を置くのは僅か15行に過ぎない。
「カナダは比較的狭小な市場であり、既存のカナダ系銀行は、確立されたブランド、広範な支店網、そして長年にわたって培われた顧客関係を有する極めて大規模な機関です」とトンプソン氏は述べた。
「参入を検討している米国の銀行にとって、カナダの個人顧客と競合するために必要なインフラを構築することは多額の費用を要する一方で、獲得できるのは、すでに比較的小規模な市場におけるごく僅かなシェアに過ぎないのです。」
ホワイトハウスは、コメント要請に対して即座の応答を差し控えるという姿勢を終始一貫して崩さなかった。
本稿は、2026年9月3日に初めて公表されたものである。
その後、2026年9月8日に改訂が施され、カナダ国内で事業を展開する米国系銀行の支店および子会社が保有する資産総額に関する記述が修正された。
当該資産の合計額は、為替相場の変動に応じて約901億米ドルに達し、9億400万米ドルではない。
September 8th, 2026
Trending Articles
Warren Buffett to Step Down as Berkshire Hathaway Chairman: The Next Stage of the Succession Plan
ウォーレン・バフェット、バークシャー・ハサウェイ会長職を退任へ:後継者計画の次段階
Warren Buffett to Step Down as Berkshire Hathaway Chairman: The Next Stage of the Succession Plan
ウォーレン・バフェット、バークシャー・ハサウェイ会長職を退任へ:後継者計画の次段階
Trump says CNN, MS NOW, and Politico are barred from the White House, targeting further news organizations
トランプ大統領、CNN、MS NOW、ポリティコのホワイトハウス立ち入り禁止を発言、さらなる報道機関を標的に
Trump says CNN, MS NOW, and Politico are barred from the White House, targeting further news organizations
トランプ大統領、CNN、MS NOW、ポリティコのホワイトハウス立ち入り禁止を発言、さらなる報道機関を標的に
Bank of Japan raises policy rate to 1.25%, highest in 31 years
日銀、政策金利を1.25%へ引き上げ、31年ぶりの高水準に
Bank of Japan raises policy rate to 1.25%, highest in 31 years
日銀、政策金利を1.25%へ引き上げ、31年ぶりの高水準に
Anthropic announced that its own model Claude is assisting in the development of a next-generation version.
Anthropic、自社モデルClaudeが次世代版の開発を支援していると発表
Anthropic announced that its own model Claude is assisting in the development of a next-generation version.
Anthropic、自社モデルClaudeが次世代版の開発を支援していると発表
The Reasons and Implications of the FRB's Current Decision to Raise Interest Rates
FRBが今、利上げに踏み切る理由とその意味
The Reasons and Implications of the FRB's Current Decision to Raise Interest Rates
FRBが今、利上げに踏み切る理由とその意味
US stocks surge most in six weeks amid falling oil prices and declining bond yields
米国株、原油安と債券利回り低下を受け6週間ぶり最大の急騰
US stocks surge most in six weeks amid falling oil prices and declining bond yields
米国株、原油安と債券利回り低下を受け6週間ぶり最大の急騰
Fed Raises Key Interest Rate for First Time in Three Years, Defying Trump's Demand for Cuts
FRB、3年ぶりに主要金利を引き上げ——利下げを求めるトランプ大統領の要求に反する決断
Fed Raises Key Interest Rate for First Time in Three Years, Defying Trump's Demand for Cuts
FRB、3年ぶりに主要金利を引き上げ——利下げを求めるトランプ大統領の要求に反する決断
Unemployment insurance claims fall to 196,000—lowest level since mid-July, layoffs remain subdued
失業保険申請件数、19万6000件へ減少—7月中旬以来の最低水準、解雇なお低調
Unemployment insurance claims fall to 196,000—lowest level since mid-July, layoffs remain subdued
失業保険申請件数、19万6000件へ減少—7月中旬以来の最低水準、解雇なお低調
President Trump dismisses AI risks as a "hoax," claims a "pathological conspiracy" surrounding AI and data centers
トランプ大統領、AIのリスクを「デマ」と一蹴し、AIとデータセンターを巡る「病的な陰謀」の存在を主張
President Trump dismisses AI risks as a "hoax," claims a "pathological conspiracy" surrounding AI and data centers
トランプ大統領、AIのリスクを「デマ」と一蹴し、AIとデータセンターを巡る「病的な陰謀」の存在を主張
Supreme Court to Decide Whether to Hear Maine Lobstermen's Challenge to GPS Boat-Tracking Requirement
Supreme Court to Decide Whether to Hear Maine Lobstermen's Challenge to GPS Boat-Tracking Requirement
Supreme Court to Decide Whether to Hear Maine Lobstermen's Challenge to GPS Boat-Tracking Requirement
Supreme Court to Decide Whether to Hear Maine Lobstermen's Challenge to GPS Boat-Tracking Requirement