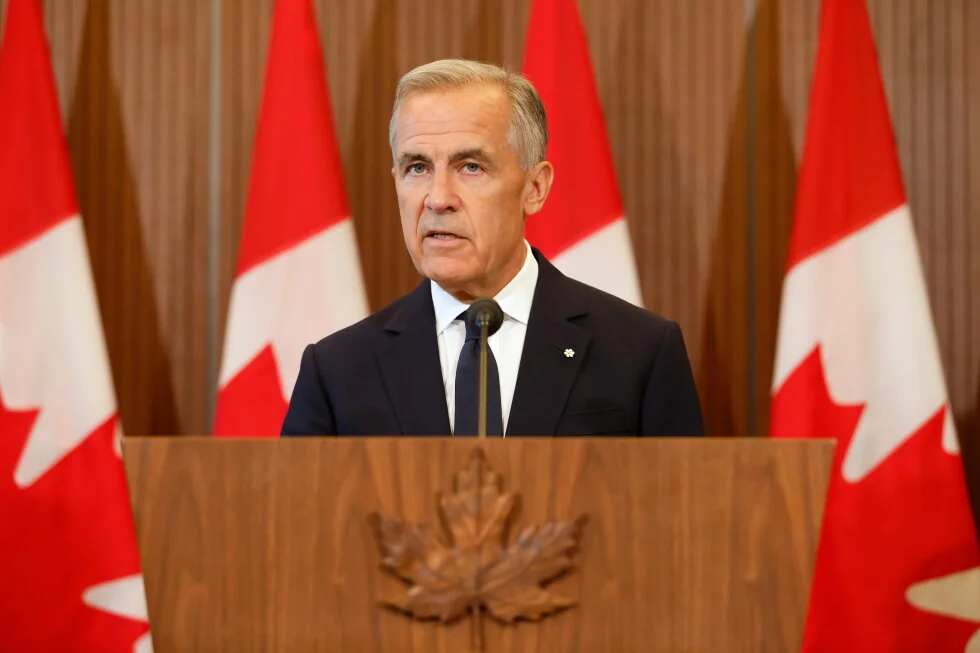
Fact check: Trump's claim that American banks cannot operate in Canada is at odds with the facts.
September 8th, 2026
Fact check: Trump's claim that American banks cannot operate in Canada is at odds with the facts.
🇺🇸 English
在週三被問及與加拿大的貿易齟齬時,總統唐納德·川普謬稱美國銀行業者受制於禁令,無法與其北方鄰國進行商業往來。
此項指控係於白宮橢圓形辦公室與美國旅遊業高層會晤之際提出,當時一名記者詢及川普,兩國之間是否存在重啟貿易談判之規劃。
專家指出,儘管美國銀行在加拿大可能遭遇若干營運上的制約,惟其並未遭受明令禁止,仍獲准於該國境內繼續從事金融業務。
以下乃對事實之縝密剖析。
川普:「彼等於此設有其銀行,即加拿大銀行,及其所有大型銀行——宏偉壯觀之銀行。
據余之判斷,彼等在此擁有六、七家主要銀行機構。
我方於彼處則未設有銀行。
君可知其緣由乎?
蓋因彼等不予准許。」
事實:據加拿大銀行家協會發言人所述,目前計有十五家美國銀行以分行或子公司之形態,於加拿大境內營運。
專家指出,若干限制或令美國銀行在加拿大市場之競爭備受阻礙,惟彼等仍可自由准入。
依聯準會最新數據觀之,有八家加拿大銀行在美國營運。
加拿大銀行則不在此列——其乃加拿大之中央銀行,職能相當於美國之聯準會,而非商業企業。
「我認為若干混淆實則源於美加兩國監管體系之間的根本性差異,」加拿大安大略省滑鐵盧大學金融學教授詹姆斯·湯普森如是闡述。
「美國銀行確實獲准於加拿大境內營運,然而其進入加拿大市場的戰略路徑選擇,將直接制約其業務拓展的範疇與深度。」
加拿大銀行體系之架構,可細分為三大類別——附表I、附表II及附表III,其中附表I專指於本土註冊之金融機構。
此類別下,共有六家主要銀行,其合併資產總額竟凌駕於國內其餘二十八家規模較小銀行之資產總和之上,此一現象,實乃該國銀行業高度集中之明證,亦凸顯其金融版圖之獨特格局。
外國實體可選擇以附表II或附表III銀行之形態營運。
附表II銀行係於加拿大註冊之外資子公司,原則上受與本國銀行相同之銀行架構規範所約束。
附表III銀行則為在加拿大註冊之外國銀行分行,不具加拿大法人資格,故須承受諸如較高存款門檻等監管限制。
多數美資銀行乃以附表III機構之身分於加拿大境內運作。
加拿大銀行家協會發言人納塔莉·貝熱龍闡述道,在加拿大境內運營的美國銀行分行及其附屬機構,其合併資產總額約莫一千二百四十億加元(折合九百零一億美元),此一數額佔外國銀行於加拿大子公司及分行所持有資產總值之半數有餘。
「此等銀行專注於涵蓋企業及商業貸款、國庫服務、信用卡產品、投資銀行業務與抵押貸款融資等範疇之綜合金融服務,」她闡述道。
「彼等不僅服務跨境商業活動之客戶群,亦同時深耕加拿大國內零售市場之廣大客層。」
在加拿大境内运营的主要美国金融机构,包括摩根大通银行、花旗银行、美国银行、第一资本及富国银行,均在此地设有举足轻重的分支机构,其业务版图之广,足以彰显其在北美金融体系中的核心地位。
由於加拿大銀行業監管框架的制約,附表II與附表III銀行均受到相應限制。
加拿大智庫C.D. Howe研究所主席兼執行長、金融與貨幣政策領域的權威學者傑里米·克羅尼克闡釋道,附表III銀行不得受理低於15萬加元(約合7萬2529美元)的存款業務,此一門檻意味著絕大多數民眾無法將其作為零售銀行使用。
他進一步補充,鑑於附表II銀行在法律層面上與其外國母公司相互獨立,此類機構必須自行建構在地資本結構與流動性體系——就銀行營運的視角而言,此乃效率低下的策略選擇。
此類監管桎梏,恐係多數美資銀行選擇不涉足加拿大市場之根本癥結。
據聯準會統計數據顯示,美國本土商業銀行總數逾三千七百家,然於加拿大境內營運者,僅區區十五家而已。
「加拿大乃一相對狹隘之市場,而現存之加拿大銀行業者已然躋身規模宏鉅之列,坐擁根深蒂固之品牌聲譽、綿密廣佈之分行網絡,以及歷久彌堅之客戶紐帶,」湯普森如是道。
「對於意欲涉足此域之美資銀行而言,欲構築足以與加拿大零售客戶群競爭之必要基建,其耗費將極為可觀,而初始階段所能斬獲之市場份額,亦僅能在這已然相對有限之市場中佔據區區一隅。」
白宮迄今尚未就相關置評請求作出任何即時回應。
此報導最初刊載於2026年9月3日,嗣於同年9月8日修訂,旨在更正加拿大境內美國銀行分行及子公司之資產數據。
彼等總資產約莫為901億美元,其數額隨匯率波動而異,而非原先所述之9.04億美元。
September 8th, 2026
Trending Articles
Buffett steps down as Berkshire chairman, succession plan enters new phase
巴菲特卸任波克夏董事長,接班布局邁向新階段
Buffett steps down as Berkshire chairman, succession plan enters new phase
巴菲特卸任波克夏董事長,接班布局邁向新階段
Trump expands crackdown on news media, barring CNN, MS NOW and Politico from the White House
川普擴大封殺新聞媒體,禁止CNN、MS NOW與Politico進入白宮
Trump expands crackdown on news media, barring CNN, MS NOW and Politico from the White House
川普擴大封殺新聞媒體,禁止CNN、MS NOW與Politico進入白宮
The Bank of Japan raised interest rates to 1.25%, setting a 31-year high.
日本央行加息至1.25%,締造31年新高
The Bank of Japan raised interest rates to 1.25%, setting a 31-year high.
日本央行加息至1.25%,締造31年新高
Anthropic says its model Claude is helping to advance the development of its own next version.
Anthropic 稱其模型 Claude 正協助推進自身下一版本的開發
Anthropic says its model Claude is helping to advance the development of its own next version.
Anthropic 稱其模型 Claude 正協助推進自身下一版本的開發
The Reasons for the Federal Reserve's Interest Rate Hikes and Their Profound Implications
聯準會升息之緣由及其深遠意涵
The Reasons for the Federal Reserve's Interest Rate Hikes and Their Profound Implications
聯準會升息之緣由及其深遠意涵
Oil Prices and Yields Retreat as US Stocks Post Best Single-Day Performance in Six Weeks
油價與殖利率回落 美股創六週最佳單日表現
Oil Prices and Yields Retreat as US Stocks Post Best Single-Day Performance in Six Weeks
油價與殖利率回落 美股創六週最佳單日表現
The Fed ignored Trump's calls for rate cuts and raised rates for the first time in three years.
聯準會無視川普降息呼籲,三年來首度升息
The Fed ignored Trump's calls for rate cuts and raised rates for the first time in three years.
聯準會無視川普降息呼籲,三年來首度升息
Jobless claims fall to 196,000, lowest since mid-July, as layoffs remain subdued
失業救濟申請降至19.6萬,創7月中以來新低,裁員持續低迷
Jobless claims fall to 196,000, lowest since mid-July, as layoffs remain subdued
失業救濟申請降至19.6萬,創7月中以來新低,裁員持續低迷
Trump decries AI risks as a "hoax," pointing directly to a "sick conspiracy" targeting AI and data centers.
川普斥AI風險為「騙局」,直指針對AI與資料中心的「病態陰謀」
Trump decries AI risks as a "hoax," pointing directly to a "sick conspiracy" targeting AI and data centers.
川普斥AI風險為「騙局」,直指針對AI與資料中心的「病態陰謀」
The Supreme Court will decide whether to hear a case in which Maine lobster fishermen challenge the GPS vessel-tracking requirement.
最高法院將裁定是否受理緬因州龍蝦漁民挑戰GPS船隻追蹤器規定一案
The Supreme Court will decide whether to hear a case in which Maine lobster fishermen challenge the GPS vessel-tracking requirement.
最高法院將裁定是否受理緬因州龍蝦漁民挑戰GPS船隻追蹤器規定一案